Begin with the objects
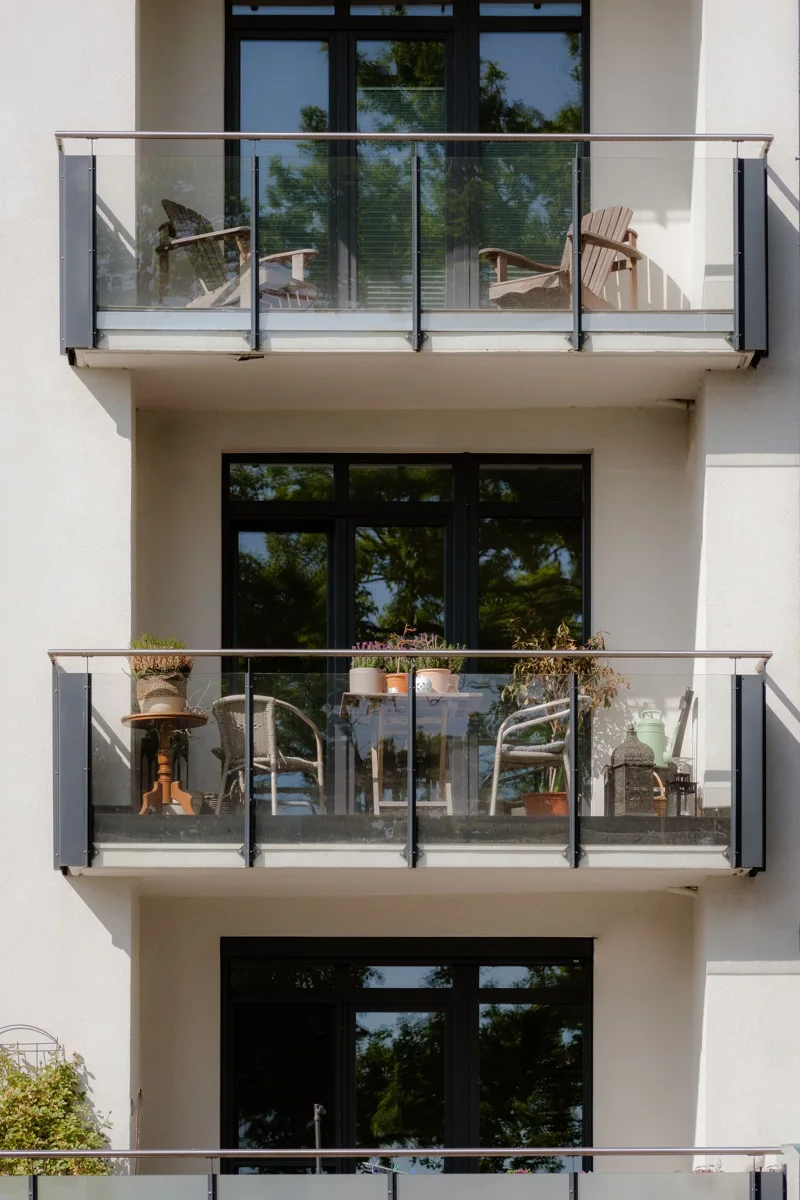
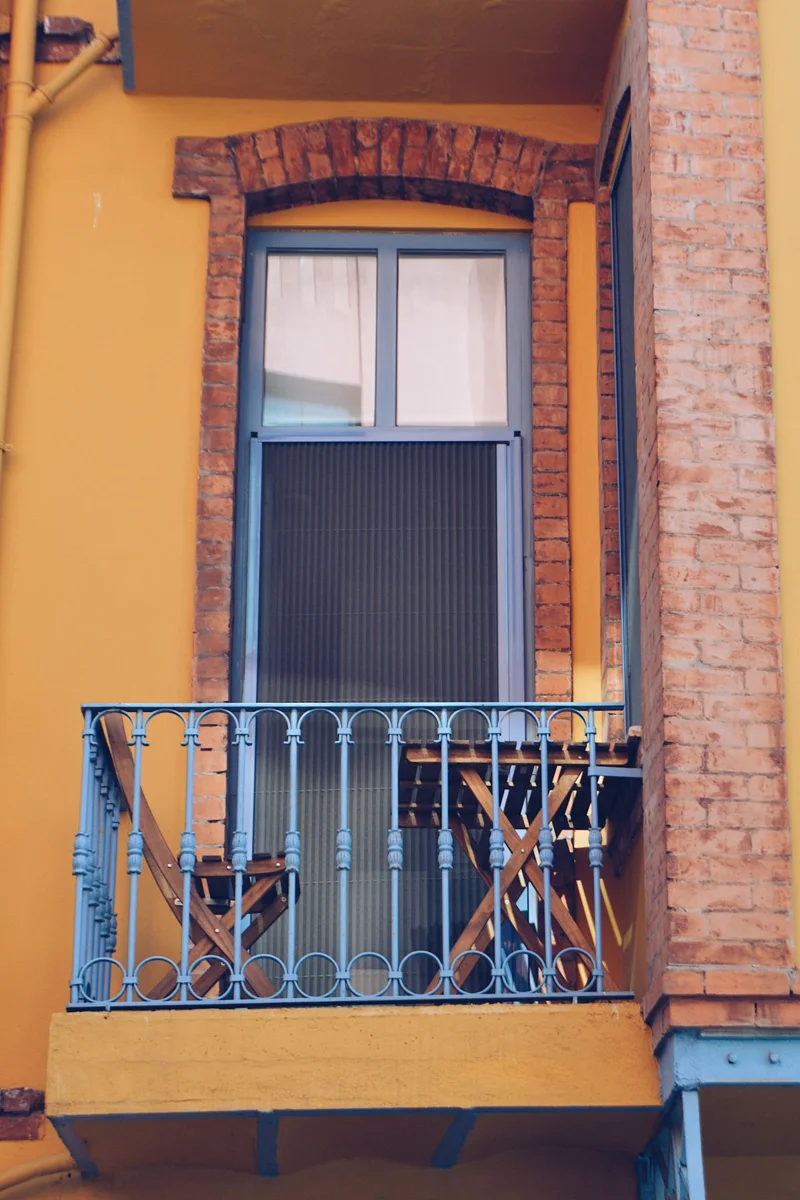
A balcony may contain folding chairs, plant containers, a freestanding storage box and a fixed balustrade. Do not combine them into one inventory entry labelled balcony. Distinguish the belongings you use from building components. In a rental or apartment, responsibility for fixed elements may also involve another party.
a.s.r. explicitly mentions balconies and roof terraces in its contents product information. A location being mentioned is a starting point rather than a promise covering every loss to everything kept outside. Check the terms for the particular object and cause as well. An eligible location and an insured event remain separate parts of the assessment.
Outside differs from the living room
Ask about the objects actually kept there using concrete examples. Chairs intended for outdoor use present a different enquiry from a laptop left on the table during a warm evening. Sharing a balcony location does not make those uses identical. Name the precise category of valuable equipment rather than subsuming it under garden furniture.
Consider the transition between indoors and outdoors. Cushions may spend winter in a storage room and summer on the balcony. Include that usual change when making an inventory. A provision for another storage place or an outbuilding may then be relevant alongside the balcony wording. The place at the time of an incident still needs to be established.
Separate the building, neighbours and personal belongings
Damage can involve several components: your chair, the balcony railing and an item on a lower balcony. Describe what was damaged and who owns it without deciding liability in advance. Reporting your own possessions does not automatically report a neighbour's loss.
Where possible, retain photographs of the original arrangement and visible damage without entering an unsafe location. Ask the landlord or building manager which documentation is available for an unclear fixed component. This keeps the initial record factual: object, location and owner, followed by the appropriate insurance question.