Describe the damage before drawing a conclusion
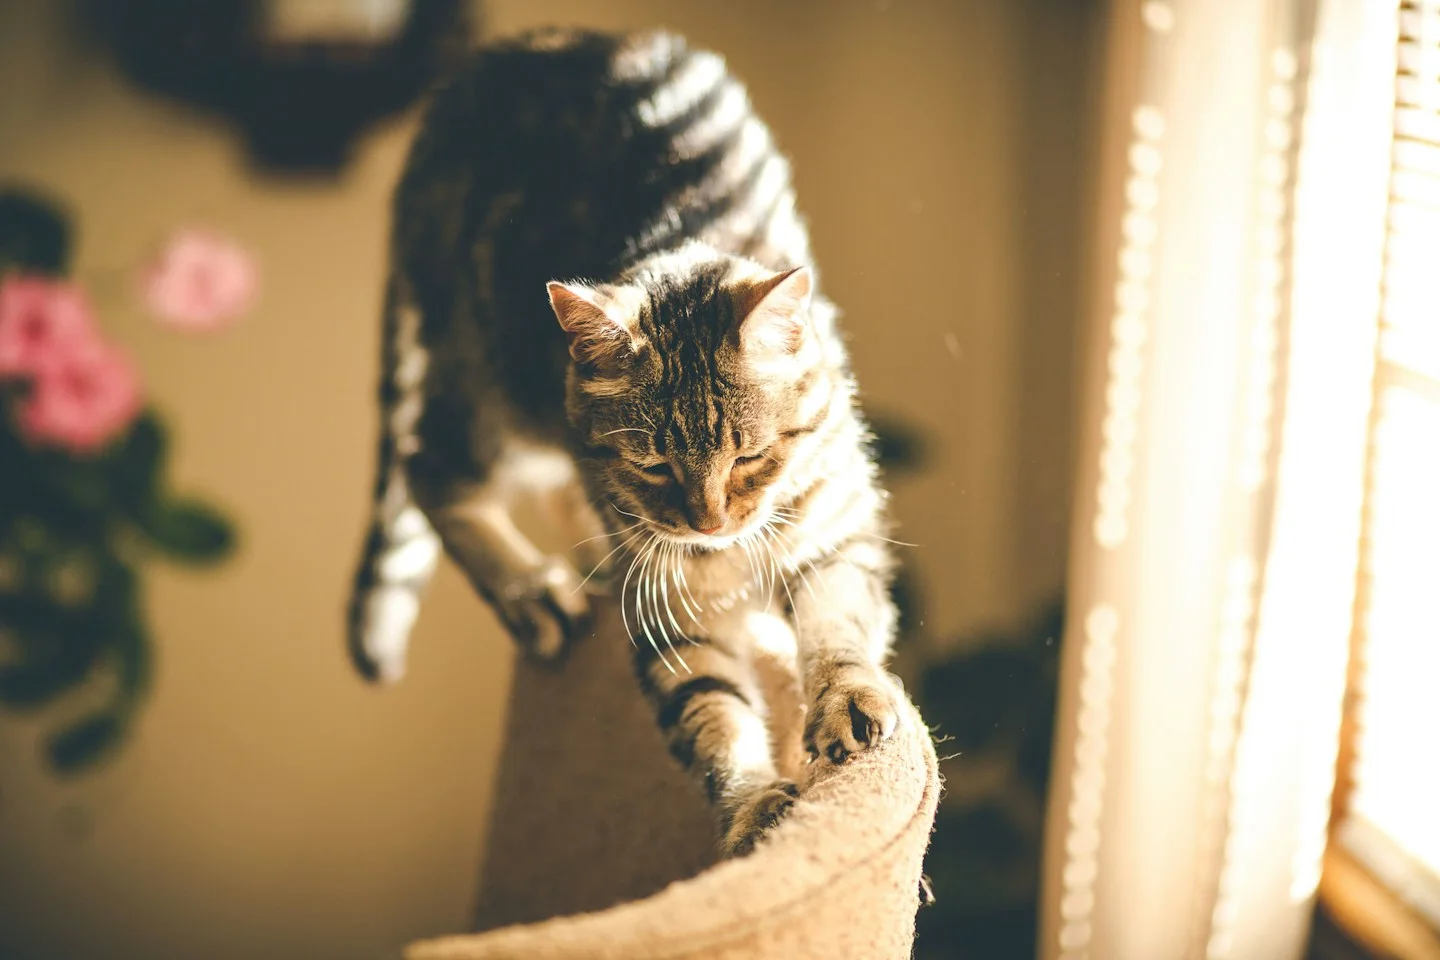
A cat scratches a sofa covering, a dog chews a remote, and an animal knocks a vase off a cabinet. Each involves a pet, but the damage and timeline differ. Record what was observed and when, with photographs identifying both the affected area and the object.
Wear visible for months needs a different account from one sudden event. Do not assign old damage a new date to make it one incident. If you do not know when damage occurred, state when you discovered it and what earlier condition can still be established.
Find the pet provision
Univé's pet page explains that damage by an owner's pets to their own contents is excluded under its described product. This demonstrates why a general accidental-damage description does not end the enquiry. Read the actual exclusion and any exceptions in your own contract.
Ask how the wording applies to the real event. Is the handler discussing direct scratching or chewing, a subsequent incident, or gradual deterioration? Identifying the object does not establish an insured cause. A sofa remains furniture even where a particular cause of damage is excluded.
If more than one explanation is possible, keep them separate. A loose seam noticed after the dog jumped onto a seat does not prove that the jump caused it. A repairer's findings may clarify the material condition without establishing everything that happened in the room.
Whose belongings and whose animal?
Liability insurance concerns a different question from insurance for your own sofa. A pet's involvement does not automatically turn your own damaged possession into a liability claim. If the object belongs to a visitor or the animal to somebody else, record ownership and the people involved. Do not assume that these facts alone settle legal responsibility.
Make a repair enquiry specific. For a sofa, an upholsterer might explain whether one panel can be repaired or why a larger section is involved. Disclose earlier damage and request separate labour and material amounts. A photograph of a pet sitting beside the sofa does not itself prove it caused a tear.
Keep a record of existing damage even if you decide not to pursue a claim after reading the wording. If another incident happens later, identifiable earlier damage helps distinguish what changed. That is more useful than describing the entire condition again as a fresh loss.