What a photograph can show
An image may establish an object's presence and appearance. It does not automatically prove ownership, exact payment or cause of later damage. Identify the question the image is intended to clarify.
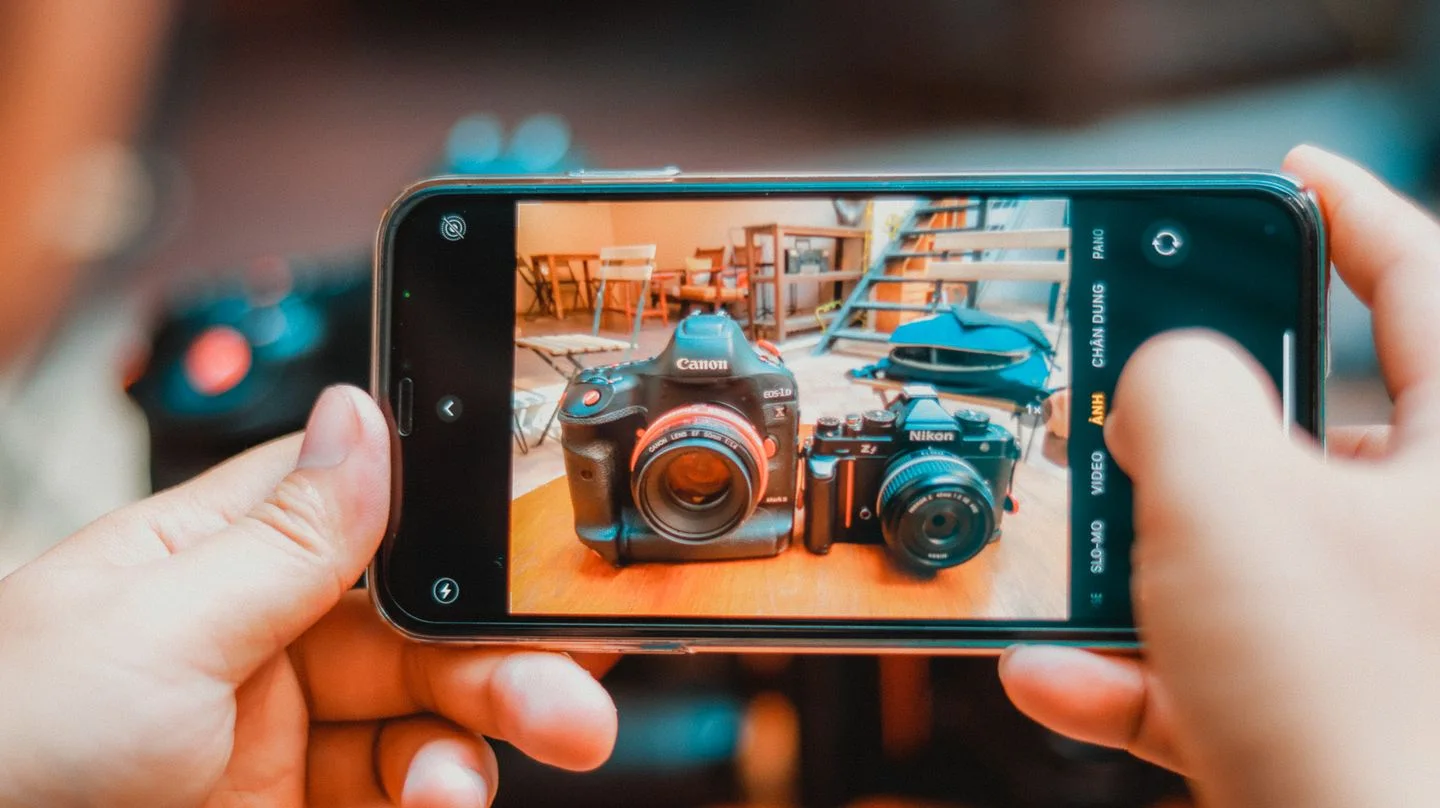
For a camera, an overview can show configuration while an existing type-label detail helps identification. Do not move it to a fictional damage location to make a file more convincing. An illustrative reconstruction must not be presented as the original circumstances.
Payment information has another purpose
An invoice or order confirmation may support purchase details. A bank statement can show payment without identifying the full specification. Keep complementary information where possible without inventing details to make documents match.
Interpolis lists purchase information, characteristics and photographs among material useful for assessment. What a particular situation requires must be established separately. A receipt does not prove every other condition is satisfied.
If another person paid or gave the item as a gift, describe that background factually. Payer, purchaser and present owner need not always coincide. Ask what clarification is needed where documents do not explain this.
The event remains separate
A complete purchase file cannot explain why damage occurred. Supply available observations with timing and location for that question, keeping assumptions separate. No known explanation is the correct description of an unresolved cause.
A clear cause does not settle contractual cover either. Facts still need assessment against relevant provisions. Ask whether missing information concerns identity, circumstances or a specific condition.
Avoid sending unrelated material on the assumption that volume equals evidence. A short explanation of what each record supports makes assessment clearer. Keep originals and identifiable versions when adding information.
Keep an incomplete file honest
Older belongings may lack records. State what exists and what cannot be located, asking about suitable alternatives without recreating a nonexistent receipt or precise date as if originally recorded.
Aim for a coherent factual description. It supports assessment without converting an excluded event into an insured one or guaranteeing an amount. That distinction keeps an organized file meaningful. When new evidence changes an earlier assumption, identify the correction rather than silently replacing the account and leaving conflicting versions unexplained.