Recognise two different processes
Considering a new insurer while an earlier claim remains open can create administrative confusion. The claim concerns an event and its subsequent assessment. The application concerns a proposed policy beginning on a particular date. Keep them alongside one another without assuming the new provider takes over the existing case.
Start with the earlier incident date, the policy under which it was reported, the case reference, and current status. Separately record the intended new start date. Switching dates and the settlement date of an earlier claim need not coincide.
Ask the existing handler about continuity
Establish how contact about the open case would work after a possible policy cancellation. Who receives further documents, where can status be checked, and what questions remain outstanding? Clarifying access and administration differs from requesting a final coverage decision.
Centraal Beheer's claims overview distinguishes open and completed notifications and explains adding documents. Check your own provider's arrangements, particularly if access or contact information may change. Keep relevant records yourself without assuming attachments sent through every channel appear in the same place.
Ask separately what the proposed policy ending means, according to the provider, for handling the incident already reported. Preserve the answer with the claim. Do not import a general rule from another product or someone else's experience.
If the provider requests an action before the switch, record exactly what it is and whether it has been completed. A personal note saying discussed should not replace the actual instruction or acknowledgement.
Answer the new application accurately
Read claim-history and pending-case questions literally. An unresolved claim has no final outcome yet. Supply the known status and seek clarification if unsure how an open case fits the wording. An expected refusal or payment should not be described as an established result.
Check what the prospective insurer accepts and from which date. A quotation or submitted form is not a confirmed policy. Do not arrange an ending based solely on an assumption that the new application will be accepted.
If the earlier claim's status changes during the application, check what remains relevant and how updated information should be provided. Keep the factual update visible rather than altering old documents to make them appear consistent with the later status.
Prevent documents crossing into the wrong file
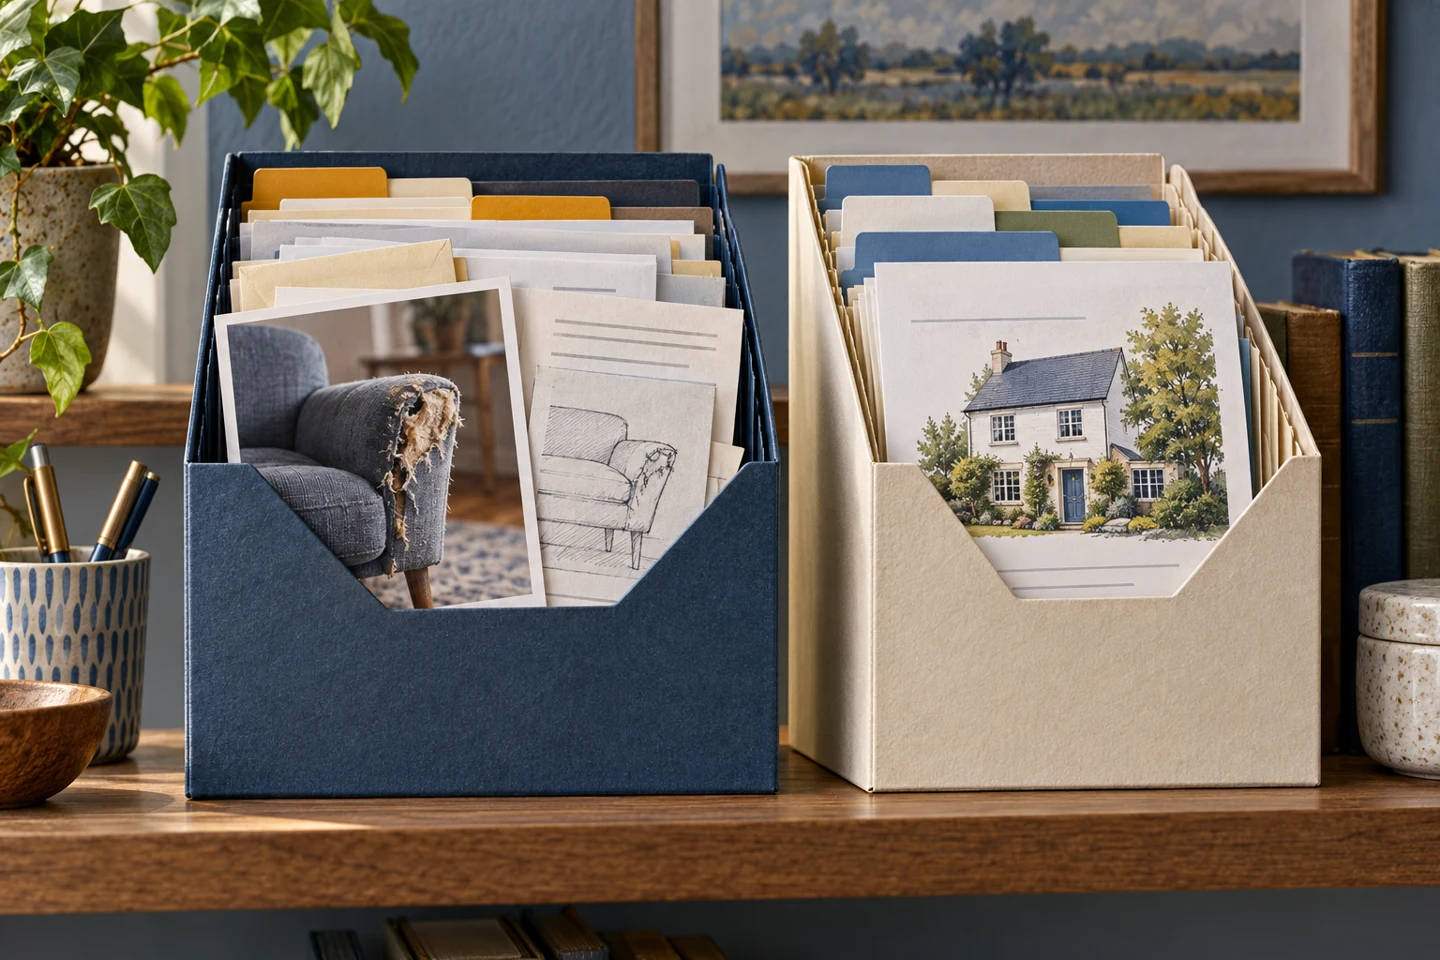
Create one file for the earlier claim and another for the new policy. Connect them with a short reference only where information is relevant to both. Do not automatically move sensitive material into the new application simply because it already exists in the old file.
Retain the earlier claim's relevant policy documents and incident correspondence. A later schedule does not automatically explain the conditions relevant to an earlier event. Identify dates clearly instead of relying on filenames alone.
A practical timeline can have three rows: the earlier incident and its handling, the old policy's ending, and the new policy's beginning. Mark only confirmed dates as final. This organises the processes without attempting to decide the legal assessment of the claim yourself.
Continue following the earlier case
After switching, make sure messages from the earlier handler still reach you and respond to specific requests through the agreed route. A new policy does not administratively complete an unanswered question in the earlier claim.
When that case closes, retain its final correspondence in the claim file. The new policy keeps its own records. You can then trace which provider communicated about which period and event without merging separate processes or assuming an outcome.